Why Crypto Exchanges Must Raise the Bar for Token Listings
A token can move from obscurity to a trading app in days. Its price, community and volume may look impressive. Yet none of those numbers tells a buyer whether the project has delivered anything, who holds the supply, or when insiders can sell. Exchanges have become the gateway to retail investors. That gate should be harder to pass.
The case for tougher listings is not a case for banning experiments, meme culture or assets whose main appeal is value storage. It is a case for making risks visible and holding platforms accountable for the tokens they choose to promote. Europe has started through MiCA. The United States is developing a different set of rules. Neither system should be mistaken for a guarantee that a listed token is worthwhile.
Why a listing matters more than a white paper
Creating a token is easy; reaching a large pool of buyers is the valuable step. A listing offers liquidity, exposure and an implied signal that somebody checked the asset. Retail customers may reasonably assume that an exchange has investigated a token before putting it beside established assets. The exchange, meanwhile, can earn fees from trading whether the project succeeds or fails. That conflict makes the quality of its listing process a public concern.
Volume alone cannot settle the question. Trading can be concentrated, subsidised or distorted. A large online community can be genuine without making the economics fair. Even a working product may have a token whose supply schedule transfers much of the upside to founders and early backers.
What EU MiCA already requires
The EU Markets in Crypto-Assets Regulation, or MiCA, generally applied from 30 December 2024; its stablecoin provisions began applying earlier. The maximum transitional period for existing crypto-asset service providers ended on 1 July 2026, though national transitions could end sooner [1]. MiCA covers several classes of crypto-assets, while financial instruments governed by existing EU securities law fall outside its main crypto-asset regime.
For many crypto-assets offered publicly or admitted to trading in the EU, MiCA requires a published white paper with information on the issuer, project, token, technology and risks. The paper must warn, among other things, that the asset may lose all its value, become illiquid and lack deposit or investor-compensation protection. The precise obligations and exceptions depend on the asset and offer [2]. Publication is disclosure, not an official stamp of quality.
MiCA also places duties directly on a trading platform. Before admission, its operator must check its own rules and assess suitability, including technical reliability and potential links to illicit or fraudulent activity, taking account of the issuer and development team. Platforms must maintain systems to prevent or detect market abuse and publish trading information [3]. These are substantial duties. MiCA does not, however, impose a universal minimum use case, a fixed number of permitted coins, or a blanket multi-year founder lock-up.
The US is moving, but along a different path
In the United States, the GENIUS Act was signed in July 2025 and established a federal framework for payment stablecoins, with rules on eligible issuers, reserves and disclosures [4]. That is significant for dollar-linked tokens. It is not a general quality test for every speculative coin sold on an exchange.
In March 2026, the Securities and Exchange Commission, with the Commodity Futures Trading Commission joining its interpretation, clarified how federal securities law applies to categories of crypto-assets and certain transactions [5]. In August, the SEC proposed Regulation Crypto Assets, a tailored offering framework for some crypto-related investment contracts with proposed disclosure and reporting conditions [6]. That proposal is not final law. A broader market-structure bill, the CLARITY Act, failed to advance in the Senate in September 2026; it should not be described as enacted [7].
For European readers, US developments matter because token issuers, liquidity providers and major exchanges operate across borders. But US legislation does not replace an EU platform’s MiCA obligations, and a token’s treatment in one jurisdiction does not certify its value in another.
The missing question: who can sell, and when?
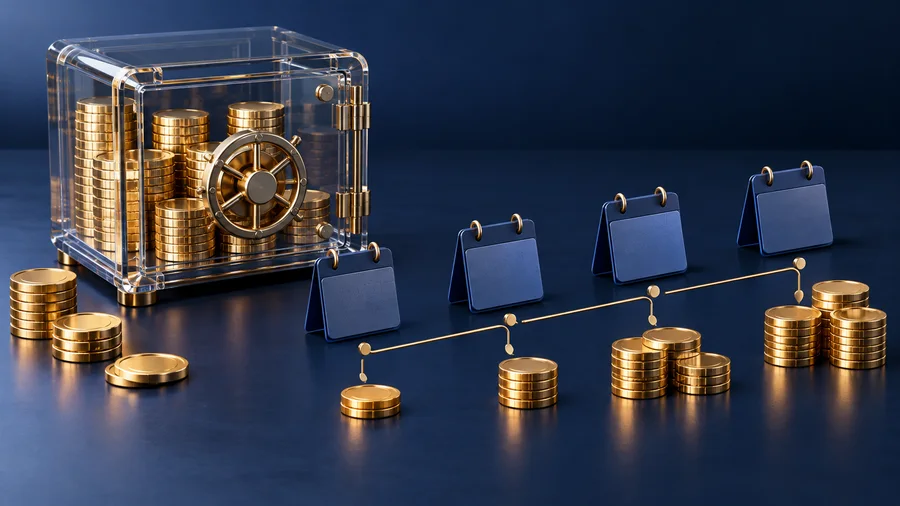
A token unlock can increase the amount of supply available for sale. It does not automatically crash the price: demand, the size of the release and holder behaviour matter. But a buyer should not need to search obscure dashboards to learn that founders or venture investors will soon receive a large allocation.
Exchanges should publish a standard, easy-to-read token supply panel before trading begins: total and circulating supply; allocations to founders, investors, treasury and community; independently verifiable vesting contracts; scheduled releases; and any power to change the schedule. Material changes should trigger prominent alerts. Where lock-ups depend only on a team’s promise rather than enforceable code or contract terms, the platform should say so plainly.
Longer, enforceable insider vesting would reduce the chance of an immediate exit into retail demand. A universal lock-up period is a blunt tool, however: it can be circumvented through derivatives, loans, related wallets or private transfers. The stronger standard combines vesting, disclosure, beneficial-ownership checks and monitoring of insider transactions.
A stronger exchange listing standard
- Verify the people and entities behind a project, its funding and any related market makers; disclose material conflicts and paid listing arrangements.
- Assess the code, control rights, security history and whether the advertised product actually exists. Explain what role the token plays, including when that role is simply speculative or cultural.
- Publish ownership concentration, float, liquidity quality and the full unlock calendar in a comparable format before the first retail trade.
- Monitor wash trading, coordinated manipulation, insider transfers and misleading marketing after listing. Reassess projects when facts change.
- Set public rules for warnings, suspension and delisting, with an orderly process that does not strand customers unnecessarily.
Regulators should set enforceable minimum standards and inspect how exchanges apply them. They need not decide which idea deserves to exist. An exchange can list a meme coin if it accurately describes the risks and meets sound market-integrity rules; a polished “utility” claim should earn no shortcut.
The real test of a regulated crypto market
A regulated platform can still offer risky assets, and investors can still lose money. The test is whether the buyer can see the risks before purchase, whether the exchange has checked the claims it can check, and whether insiders face consequences for hiding material facts. MiCA provides Europe with a meaningful starting point. The next step is to turn listing diligence, unlock transparency and continuing surveillance into standards that customers can actually see.
Crypto does not need a government committee to approve every idea. It does need exchanges to stop treating access to retail buyers as a reward for hype alone.
Frequently asked questions
Does MiCA approve crypto tokens?
No. MiCA creates disclosure and platform obligations; publication of a white paper does not mean a regulator endorses a token [2].
Does MiCA require every crypto token to have a use case?
No universal utility test appears in its trading-platform suitability rules. The relevant duties concern disclosure, platform rules, technical reliability and risks including fraud [3].
Are token lock-ups required in the EU?
MiCA does not impose a blanket lock-up period on founders for every token. A particular token may have contractual vesting, and relevant supply information should be disclosed where required.
Has the US passed a law covering all crypto exchange listings?
No. The GENIUS Act addresses payment stablecoins; broader market-structure legislation has not been enacted as of 27 September 2026 [4, 7].
Sources and editorial note
[1] ESMA, MiCA Articles 149 and 143: Source ; Additional source
[2] ESMA, MiCA Articles 5 and 6: Source ; Additional source
[3] ESMA, MiCA Article 76: Source
[4] White House, GENIUS Act fact sheet, 18 July 2025: Source
[5] SEC, joint interpretation, 17 March 2026: Source
[6] SEC, proposed Regulation Crypto Assets, 18 August 2026: Source
[7] Associated Press, Senate vote, 15 September 2026: Source
Editorial position: Recommendations on listing standards and lock-ups are The Strategic Newb’s analysis, not descriptions of existing legal requirements. This article is general information, not investment or legal advice.